
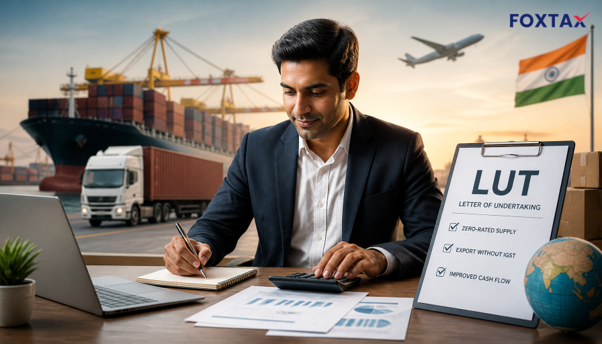
Every Indian business, of any size, which is involved in export business (of services or products) must necessarily manage cash flows. It can be quite a burden when you have to wait for GST refunds, and this can have a lot of impact on working capital. The Letter of Undertaking (LUT) filing under GST is an essential provision and opens a huge cash-flow benefit to exporters by offering them the opportunity to export without paying the Integrated Goods and Services Tax (IGST) at the time of export. Let’s understand the fundamentals of LUT, from applicability to registration, to ensuring regulatory compliance.
What Is LUT in Export and How Does It Work in India?
LUT in GST is Letter of Undertaking that you give to the GST department. Its primary function is to enable the supply of zero-rated supplies (exports) without having to pay IGST upfront. Using an LUT for export without IGST, you agree to meet the terms of the export, such as earning foreign exchange revenue within the time frame.
The Two Routes for Exporting Under GST
When exporting, it’s like you’re at a fork in the road. Make the right choice, and it can have a big impact on your cash flow. Here are your two choices:
- Export with LUT: You provide an LUT (Form GST RFD-11) and export your services or products without IGST. This is the most common way as it does not tie up your working capital.
- Export with IGST Payment: In this method, you export goods or services, pay the applicable IGST at the time of export, and later apply to the government for a refund of the IGST paid. This option is chosen by those who are not eligible to furnish an LUT or who prefer to follow the refund process.
LUT is applicable to one financial year and should be renewed on a yearly basis. As per Circular No. 8/8/2017-GST dated 4th October 2017, exporters are allowed to upload LUT online. It is a part of the zero-rated supply compliance system.
Is LUT Mandatory for Export of Services?
This is the big question. The answer is: LUT is not required for export, but it is required for export without paying IGST. To put it more simply, you are not prohibited by law from exporting without LUT.
Yet, you can always pay IGST and claim it back by way of refund, but the only option to avail the export without payment of IGST is to have an LUT, which directly affects your working capital.
Who Is Eligible for LUT and the Bond Alternative?
The broad definition makes LUT open to almost all taxpayers, but there are a few exceptions as well. Any taxpayer registered under GST who supplies zero-rated goods/services can file an LUT. But, specified persons who have been convicted of any offence under the GST Act or other specified laws can’t apply for LUT.
They will have to provide Bond with a bank guarantee of 15% of the Bond amount (Rule 96A of the CGST Rules). The minimum guarantee of 15% indicates how much a government relies on taxpayer goodwill in applying for LUT. For most taxpayers, a simple LUT certificate for export in their GST return suffices, but for more complex transactions, it’s important to read about exceptions. Contact experts like Foxtax to find out what instruments (LUT or Bond) apply to your situation.
What Are the Documents Required for Export of Services Under GST?
Complying with export regulations takes a clear documentation trail. If you export under an LUT, you must maintain a prescribed set of records. These documents are not only for your own records, but are also essential for GSTR-1 reporting and any potential refund claims. They form the backbone of your zero-rated supply compliance.
Key Documentation for LUT-Based Exports
To ensure a hassle-free export process, keep these documents ready:
- LUT in Form GST RFD-11: Unique Acknowledgement Reference (ARN) is provided to you once your LUT is approved. This ARN acts as the receipt when you file the LUT and has to be quoted by you on the export invoices of a particular financial year.
- Export Invoice: The export invoice should be a regular tax invoice with an indication that the supply is for export and the use of LUT ARN. This is sometimes called the “LUT number in invoice.”
- Bank Realisation Certificate (BRC) or Foreign Inward Remittance Certificate (FIRC): The realisation of an equivalent foreign exchange is necessary for a zero-rated supply, which can be produced by a certificate issued by your bank.
- Shipping Bill or Air Waybill: For goods, the shipping bill is essential. For services, the air waybill or other evidence of service delivery is required to support the export.
- GSTR-1 and GSTR-3B Filings: Properly declare your zero-rated supplies in GSTR-1, Table 6A. GSTR-3B has to be filled out with the same information as well. For end-to-end assistance, explore GST return filing services.
- Form GST RFD-01: When you follow the IGST paid method, the refund application is submitted by filling Form GST RFD-01.
Final Checklist for Exporting Under LUT
So to summarise, here’s a quick checklist for a compliant LUT based export process:
- Make sure you have a valid, renewed LUT for this financial year.
- Include the LUT ARN on each export invoice.
- Prepare the export and arrange supporting documents such as the invoice, shipping bill, and others.
- Make sure forex can be achieved in the given time period (normally 3 months).
- Ensures you report the zero-rated supplies properly in your GSTR-1 and GSTR-3B returns.
- Keep all documentation in case you are audited or asked questions about it.
What does an Indian exporter get from this? In essence, the Letter of Undertaking becomes an important document for any Indian Exporters, with an edge of saving working capital. While it is not a must for exporting per se, it is the undisputed portal for the zero-rated supply with no advance IGST.
Importantly, consider when to use it, the annual renewal policy as well as its documentation aspect that would pave the way for a seamless experience in filing and complying with GST. If a business is unsure or needs support, having a GST partner like Foxtax at its disposal could help it sail through without the stress.
Frequently Asked Questions (FAQ)
Can we export services without LUT?
Yes, you can. Services can be exported without an LUT. But, then you are required to pay IGST first on export and claim a refund after that. LUT is not mandatory as export without LUT is possible, only if you opt for this “pay and refund” mechanism.
Why is LUT required for export?
An LUT is required to export without the upfront payment of IGST. It is a legal undertaking to the government that you will fulfill your export obligations, including the realisation of export proceeds. This facility prevents your working capital from being locked up in IGST payments, which would otherwise be reimbursed later.
Is it mandatory to file LUT under GST?
LUT filing is a requirement if you are exporting goods or services without paying IGST. Because of this, it is a requirement or rule only when exporting goods or services without paying IGST. If you pay IGST at the time of export, then you are not required to file an LUT.
Is LUT mandatory for export of goods?
No, the procedure is same for good as well as services. LUT is required only if you, as an exporter of goods, do not want to pay IGST at the time of export. Alternatively, you can pay IGST and later claim a refund through the shipping bill.